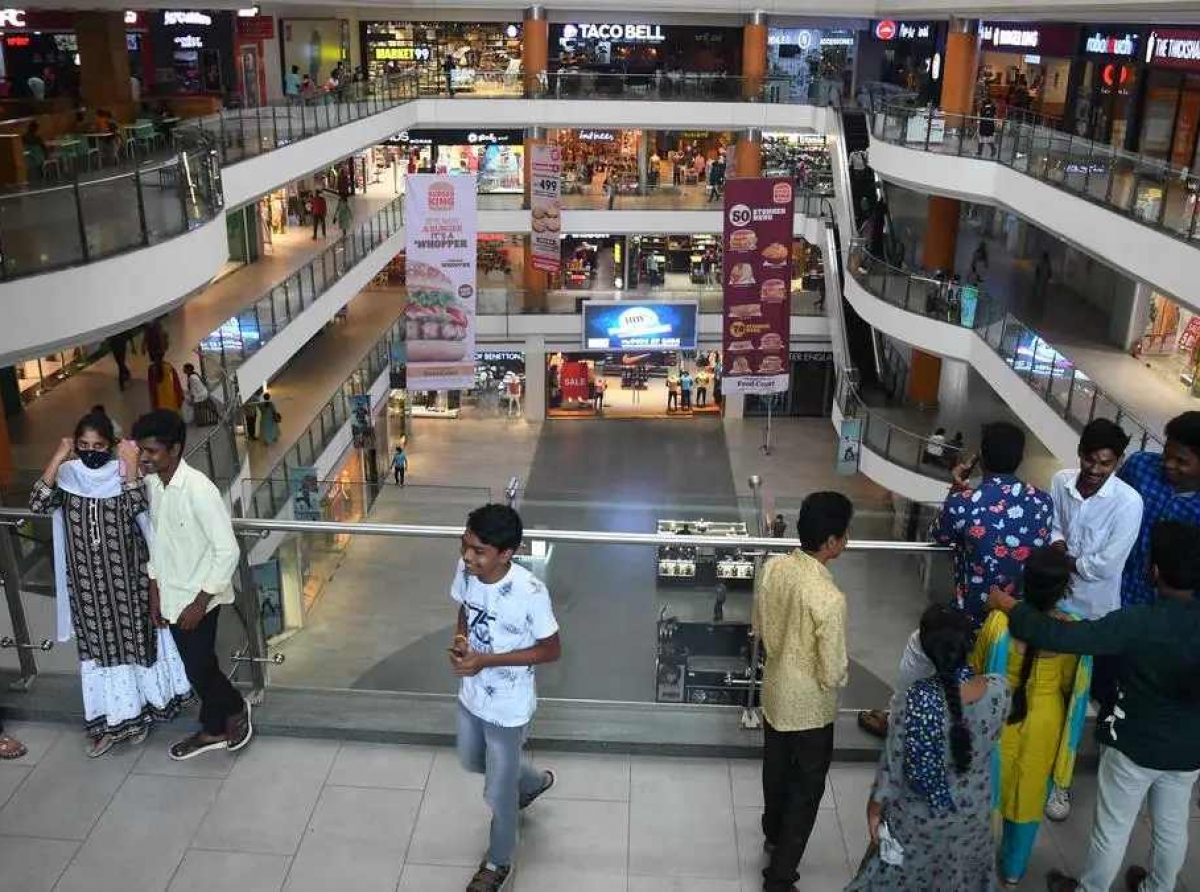
India’s consumption is in a sharply segmented phase, with the country projected to become home to 108 million affluent consumers by 2036, overtaking China’s 103 million, says a joint study by NielsenIQ (NIQ) and World Data Lab study. The affluent cohort is defined by daily expenditure of over $90, rather than conventional wealth or asset ownership. From 26 million people in 2026, India is expected to add 82 million affluent consumers over the next decade, the largest absolute increase globally. China is projected to add 62 million during the same period.
Yet the opportunity is not confined to the top end. India also has 649 million core consumers spending between $13 and $90 a day, creating a market where premiumisation and value consciousness will coexist.
Table: India’s consumer market over view
|
Consumer segment/market (2026-36) |
Affluent count 2036 (mn) |
Net growth from 2026 (mn) |
|
United States |
231 |
+31 |
|
India |
108 |
+82 |
|
China |
103 |
+62 |
|
Germany |
32 |
+5 |
|
Japan |
30 |
+5 |
|
United Kingdom |
27 |
+6 |
|
Brazil |
23 |
+8 |
|
Rest of World |
471 |
+170 |
|
Global Total |
1,025 |
+369 |
Source: World Data Lab, NielsenIQ
Globally, the affluent segment is already disproportionately powerful. Although affluent consumers number 657 million against 4.1 billion core consumers in 2026, their annual expenditure is projected at $35.9 trillion, compared with $31.6 trillion for the much larger core segment.
Premium meets value
For Indian retailers, however, the growth in affluent consumers does not translate into an across-the-board luxury boom. India remains a volume-growth market whose sheer population scale creates significant consumption potential. Experience so far also shows that projections of middle-class growth do not always translate into sustained purchases of high-ticket discretionary goods. Wealth concentration, currency movements, real-estate constraints and import duties have historically restricted the depth of premium consumption.
The latest consumer behaviour indicators reinforce this caution. Among upgrade buyers, 60 per cent prioritise value for money and 46 per cent seek convenience. This means consumers may be willing to move up the price ladder, but only when the additional value is clearly visible.
Table: Projections vs consumption realities
|
Market characteristic |
India market context |
Implication for retailers |
|
Consumer Classification |
Volume growth market driven by scale |
Expand entry points; avoid single-price assumptions |
|
Value Orientation |
60% of upgrade buyers demand clear value |
Premium pricing requires tangible product differentiation |
|
Inflationary Impact |
26% increase in global consumer prices (2021–2025) |
Margin defense requires operational cost controls |
|
Spending Threshold |
High spenders spend >$90/day; core spend $13–$90/day |
Distinct assortments needed for affluent versus core buyers |
This bifurcation is becoming particularly important in fashion, where retailers have to balance aspiration with affordability rather than assume that rising incomes automatically create luxury demand.
Fashion builds a two-tier market
India’s fashion and luxury apparel market was valued at $9.85 billion in 2025 and is projected to reach $15.17 billion by 2034. Clothing and apparel account for 61 per cent of luxury fashion demand, supported by ceremonial dressing, occasion wear and premium western apparel. Women’s apparel makes up 52 per cent of category sales, reflecting rising workforce participation and increasing discretionary expenditure. North India accounts for about 30 per cent of luxury apparel demand, supported by wedding expenditure, affluent households and dense premium retail infrastructure across Delhi-NCR.
The implication is that fashion companies can no longer rely on a single retail pattern. Premium consumers require curation, service and exclusivity, while aspirational customers need accessible price points and convenience. For retailers, the emerging model is therefore less about choosing between mass and luxury and more about building distinct propositions for each consumer tier.
Stores regain importance
Physical retail remains central to high-end fashion, contributing around 70 per cent of luxury fashion revenue. For premium customers, stores offer functions that online channels cannot fully replicate, including personalised styling, alterations, product discovery and immersive brand experiences. The increase in Grade-A retail destinations is consequently reinforcing physical luxury. Developments such as Jio World Plaza in Mumbai and premium DLF properties in Delhi-NCR are creating international-standard environments for global brands and Indian designers.
Flagship stores are becoming experience centres, hosting private appointments, capsule launches and high-value customer events. Digital channels, meanwhile, allow brands to extend their reach into smaller cities without replicating the cost structure of a flagship store.
Reliance bets on portfolio discipline
Reliance Brands Limited (RBL) showcases how India’s premium market is being approached through portfolio management rather than indiscriminate expansion. RBL, the luxury and lifestyle arm of Reliance Retail, operates over 50 global labels, including Burberry, Diesel and Stella McCartney, alongside Indian designer partnerships. Its network includes 935 exclusive stores and 762 shop-in-shops.
The company reported FY26 revenue of Rs 3,494 crore, up 44.6 per cent year on year, while narrowing its net loss to Rs 137 crore. The performance reflects focus on closing non-viable stores, rationalising operations and concentrating investment around stronger brands and locations. Its portfolio also shows the importance of balancing high-margin luxury with categories capable of generating more frequent purchases. Premium beauty, for instance, can give greater transaction frequency than occasional luxury apparel purchases.
New retail equation
Increase in India’s affluent class gives luxury and premium retailers a substantial long-term opportunity, but the market will not evolve into a uniformly affluent consumer base. Instead, the next phase is likely to produce a highly stratified retail economy. At one end, affluent consumers will support flagship stores, luxury labels, private shopping and premium occasion wear. At the other, hundreds of millions of core consumers will remain highly sensitive to value, convenience and price.
The winners are likely to be retailers that recognise this divide early. Rather than pushing every customer towards premium products, brands will need differentiated assortments, store formats and digital strategies. India’s affluent increase, therefore, is less a signal for retailers to simply raise prices than a cue to redesign the market around multiple consumption tiers with luxury growing at the top while value remains decisive across the broader consumer base.


 Get in Touch!

